
Introduction
Payroll fraud continues to be one of the most relentless and detrimental challenges to municipal finances. The Kimberley Serious Commercial Crimes Court’s recent conviction of Mandy Kelebogile Ntshoe has once again drawn focus to how money is managed in local government. This case serves as a practical reminder of the legal framework that regulates public finance management, the repercussions of fraud, and the significance of proactive risk mitigation.
Overview of the Case
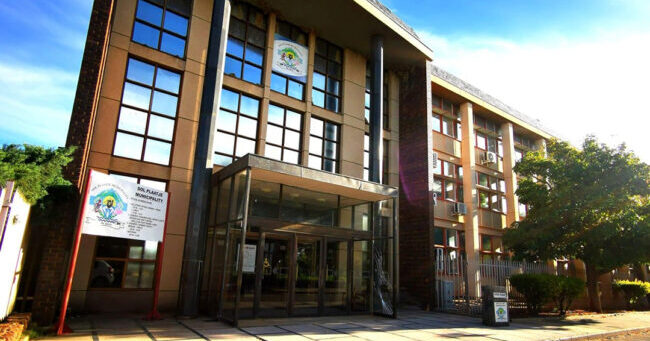
From January 2011 to December 2016, the Sol Plaatje Local Municipality compensated “ghost employees” who were never employed there. The Hawks found that unauthorised bank accounts had been added to the payroll, which led to the municipality losing an extensive amount of money.
Ntshoe was arrested in March 2021 and charged with fraud and money laundering under the Prevention of Organised Crime Act 121 of 1998 (POCA). She was sentenced to 18 months in prison or a fine of R100 000.00. Her personal involvement led to about R778,000.00, while the larger investigation revealed that systemic payroll control oversights cost millions of rands.
Legal Principles and Case Law
This case reinforces a number of fundamental legal concepts:
1. Elements of Fraud
In South African law, fraud is defined as:
“a deliberate misrepresentation or concealment of facts to induce another party to act, causing them actual or potential prejudice.”
– S v Gardener 2011 (1) SA 406 (SCA)
The elements of misrepresentation, unlawfulness, and prejudice were evidently satisfied through the use of fictitious employees and the diversion of municipal funds.
2. Money Laundering
POCA was contravened when salary payments were laundered through the bank accounts of ghost workers.
POCA, s 4(1): “Any person who knows or ought reasonably to have known that property is or forms part of the proceeds of unlawful activities and enters into any agreement … which has or is likely to have the effect- of concealing or disguising the nature, source, location, disposition or movement of the said property … shall be guilty of an offence.”
In S v Shaik and Others (CCT 86/07 [2008] ZACC 7, this section was extensively interpreted to mean that money obtained from illegal activities is considered “proceeds of crime.”
3. The Duty of Municipal Oversight
It is the legal responsibility of municipalities to establish and sustain efficient financial control systems.
Section 62(1)(c) of the Municipal Finance Management Act (MFMA) (Act 56 of 2003) places a crucial responsibility on the municipal manager to oversee the municipal financial management: “The accounting officer of a municipality is responsible for managing the financial administration of the municipality, and must for this purpose take all reasonable steps to ensure that the municipality has and maintains effective, efficient and transparent systems of financial and risk management and internal control.”
The Labour Court has continuously underscored the need for accurate payroll controls, saying that not having such harms both financial accountability and employee relations.
4. Recovering losses through civil action
The municipality can retrieve losses through civil action or asset forfeiture in addition to criminal procedures. Forfeiture of assets will need to be connected to the unlawful activities on a balance of probabilities.
Risk Management Lessons and Governance
Employers in the private sector and municipalities alike should take note of this case.
Some of the measures that are recommended are Separation of Duties:
- Separate the tasks of entering payroll, approving it, and paying it to lower the chances of fraud.
- Regular Payroll Audits: Check personnel records against payroll data and do “head counts” on a regular basis.
- Whistle-blower Protection: Make internal reporting channels stronger in compliance with the Protected Disclosures Act 26 of 2000 to encourage people to report problems early.
- Data Analytics: Use forensic data technologies to find any information that don’t make sense, including payments to dismissed staff members or overlapping bank accounts.
Conclusion
The Sol Plaatje ghost worker case is an expression of caution about what might happen when internal controls and oversight fail. The sentence given to Ntshoe shows that courts are increasingly inclined to hold people criminally responsible for payroll fraud and other money-laundering crimes.
This case emphasises the necessity for legal practitioners, compliance officers, and municipal administrators to:
• Establish comprehensive control frameworks,
• Conduct routine forensic evaluations, and
• Act decisively when irregularities are identified.
This action can help to re-establish public trust in municipal administration and prevent the occurrence of similar significant losses in the future.
Written by:
Natascha Miller
Attorney, Conveyancer and Forensic Consultant
Cell: 082 445 7003
natascham@bnlaw.co.za


